How Southeast Asias Homegrown Coffee Chains Are Outpacing Starbucks In Jakarta, Kuala Lumpur, Manila, Singapore, And Beyond
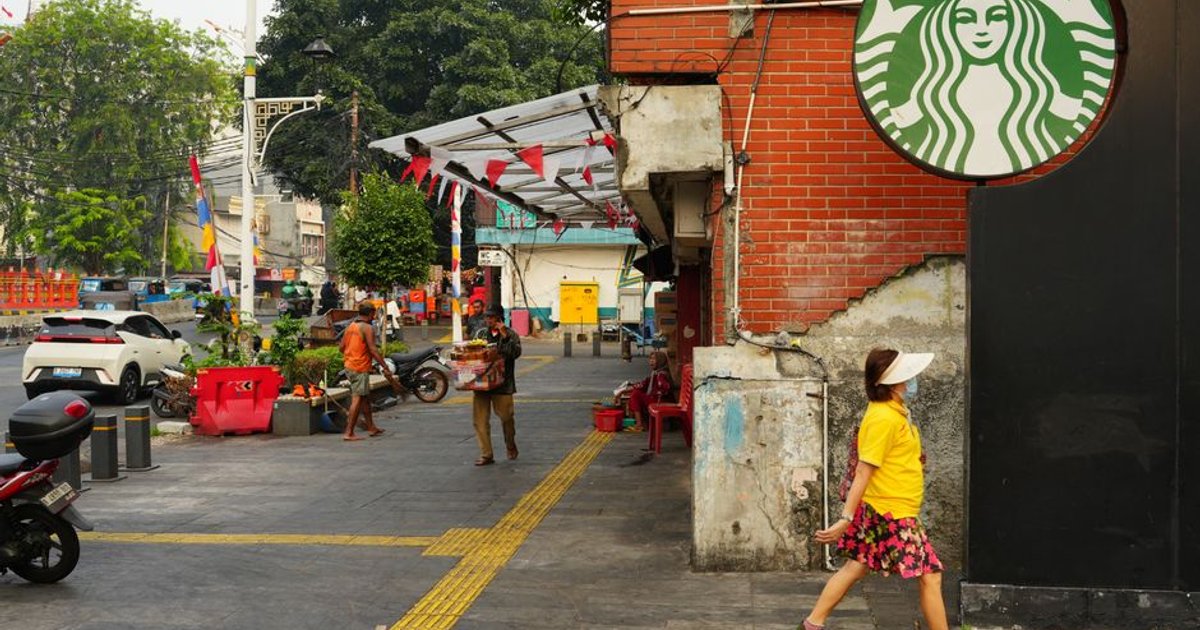
Southeast Asia’s Coffee Chain Revolution: Outpacing Starbucks, Shaping New Global Playbooks
In the energetic cities and sprawling towns of Southeast Asia, a quiet revolution has taken place. The region’s homegrown coffee chains, once dismissed as low-scale local upstarts, are now outgrowing global giants like Starbucks through price, speed, digital innovation, and deep cultural localization. The market, valued at nearly US$9.9 billion in 2025, has seen a surge in affordable-premium brands such as Kopi Kenangan, Fore Coffee, and ZUS Coffee, marking a tectonic shift in consumer expectations and retail strategy. This exposé uncovers the data, strategy, and real-world implications of Southeast Asia’s coffee chain transformation, exploring how it challenges global models, and what it signals for future retail landscapes.
The Rise of Southeast Asian “Affordable Premium” Coffee Chains
Historical Roots and Market Momentum. Southeast Asia’s coffee culture has long blended street stalls, local beans, and community rituals. Yet in the past decade, demographic shifts, urbanization, and digital penetration have fueled a modern coffee-and-tea market that soared from US$8.3 billion in 2023 to nearly US$9.9 billion in 2025 (Momentum Works research). Chains like Kopi Kenangan illustrate the new model: the brand’s reported revenue grew 45% to US$184 million in 2025, while it reached 1,324 outlets across six countries, outperforming legacy café formats.
Key Competitive Drivers. The surge is not just about local versus global, but a business model evolution. Starbucks sells a global premium café experience, leveraging brand equity, larger stores, and customization. Southeast Asian challengers offer affordable, digitally ordered coffee optimized for frequent consumption, delivery, and neighborhood accessibility. Chinese entrants like Luckin and Cotti add extreme speed, kiosk economics, and app-led promotion.
Strategic Pricing: The “Sandwich” Effect. Kopi Kenangan’s core product, Kopi Kenangan Mantan, a palm-sugar latte, retails at about Rp22,000 (US$1.30), bridging street-vendor coffee (Rp5,000, or US$0.33) and international café beverages (Rp40,000, 50,000, or US$2.50, 3.25). This price architecture expands the addressable market, making branded quality a routine purchase, not a luxury event.
Rapid Store Growth and Profitability. Kopi Kenangan’s footprint, reportedly 85% grab-and-go kiosks, enables rapid scale with lower rent, labor, and operational costs. Fore Coffee recorded Rp1.5 trillion (US$88 million) in 2025 revenue, raising US$21 million in an oversubscribed IPO and opening nearly 60 stores in half a year (World Coffee Portal). The relentless expansion of outlets and retail points illustrates how agile, lower-cost models are winning over both urban and suburban consumers.
Patterns of Localization and Digital Innovation
Cultural Relevance as Core Differentiator. Starbucks’ global consistency can become a liability in markets yearning for flavors, rituals, and language familiar to local consumers. Chains like Kopi Kenangan have mastered not only pricing, but deep adaptation: signature drinks with palm sugar, gula aren, pandan, and condensed milk; humorous and emotionally resonant names; and operation hours seamlessly aligned with urban commuting and late-night habits.
Localized Store Formats. The network strategy pivots away from large cafés to high-density grab-and-go kiosks near offices, transit hubs, and residential neighborhoods. These smaller, faster outlets reduce capital expenditure, boost throughput, and enable delivery integration, critical as delivery apps become a channel for nearly half of Kopi Kenangan's reported sales (Mission Media Asia).
App-Led Ordering and Promotion. Southeast Asian chains like Kopi Kenangan now boast roughly 1.5 million active app users, with loyalty programs and app-exclusive promotions driving repeat purchases and allowing ultra-targeted discounts. Digital wallets, super-app integrations, and influencer-led campaigns via TikTok and Instagram fuel daily frequency, making coffee a digital habit as much as a beverage.
Multichannel Monetization. Chains are expanding beyond cafés into bottled RTD (ready-to-drink) coffee, vending more than 50,000 retail points at price points ranging from US$0.60 to US$1.50, broadening brand engagement and consumption occasions. This strategy is crucial for building resilience beyond physical stores.
Comparative Perspectives: Global Giants vs. Local Champions
Starbucks: Premium Experience and Limitations. Starbucks enjoys enduring strengths, consistent quality, comfortable stores, extensive customization, and established loyalty infrastructure. It is most defensible when customers seek space, status, or service, not just a caffeine boost. However, its higher pricing and slower adaptation to local flavors make it less competitive among high-frequency, price-sensitive Southeast Asian consumers.
Southeast Asian Chains: “Affordable Premium” for the Mass Market. Brands like Kopi Kenangan and Fore Coffee combine branded packaging and consistent quality with prices accessible multiple times per week. Their strength lies in executing “third-wave coffee taste at second-wave prices,” using digital-first campaigns and rapid product cycling to keep pace with evolving local trends. Their 75% revenue concentration in Indonesia highlights both market mastery and the challenge of internationalizing deeply local products.
Chinese Entrants: Efficiency, Speed, and Pricing Warfare. Luckin and Cotti Coffee import app-led, ultra-fast kiosk models, undercutting Starbucks by 20, 25% in price. They leverage centralized procurement, limited seating, and aggressive app promotions to capture price-sensitive customers and rapidly expand. Sustained discounting, however, risks damaging profitability when promotional intensity wanes.
Independent Cafés and Other Chains. Vietnamese market leader Highlands Coffee, Malaysia’s ZUS Coffee, and specialist independents carve out niches based on authenticity, specialty beans, or urban branding. Their competitive exposure is market crowding, quality control, and the ability to scale digital convenience.
Inside the New Economics: Pricing, Place, Product, and Promotion
Pricing Strategy: Beyond Discounts. Local chains deploy a “good-better-best” framework, acquiring price-sensitive customers with entry-level RTD products, driving frequency with affordable-premium lattes, and raising ticket size through limited-edition specialty drinks. Kopi Kenangan keeps core prices below international chains while remaining above informal coffee, anchoring psychological value and habitual consumption.
Store Format and Location. The highest-growth outlets are small, quick-service points that optimize for delivery, mobile pickup, and high transaction throughput. Kopi Kenangan’s 1,324 outlets exemplify density as a competitive moat, while plans to reach 2,600 Indonesian shops and 800 in Malaysia by 2030 highlight regional ambition (Forbes).
Product Innovation. Local chains exploit Southeast Asia’s rich flavor palette, launching palm-sugar lattes, cheese foam, coconut, and seasonal tea combinations. Fast menu adaptation, enabled by digital data, lets brands respond to viral trends and local demand quickly. Diversification into snacks, light meals, and bottled offerings further increase monetization opportunities.
Promotion as Frequency Engine. The winning chains use promotion not just for awareness, but to drive repeat purchase. App-based rewards, salary-cycle discounts, limited-time flavors, and gamified loyalty programs move coffee from an occasional treat to a routine habit.
Porter’s Five Forces: Decoding the Competitive Landscape
Rivalry Among Competitors: Very High. The market is crowded, with global chains, national champions, specialty cafés, convenience stores, street vendors, and aggressive Chinese entrants fighting for share. Differentiation relies on brand meaning, speed, digital loyalty, and product adaptability.
Threat of New Entrants: Moderate to High. Opening a café is easy, but scaling profitably is difficult. Entry barriers include brand-building, store density, technology investment, procurement scale, and quality control. Kiosk models and delivery apps reduce friction, yet scaling and retention remain challenging.
Bargaining Power of Suppliers: Moderate. Larger chains negotiate better contracts, but smaller operators face volatility in coffee, milk, packaging costs, and currency swings. Supply-chain resilience and vertical integration become increasingly strategic.
Bargaining Power of Buyers: High. Consumers enjoy many options, with minimal switching costs. Loyalty programs must offer real value to retain customers, but convenience and price remain dominant.
Threat of Substitutes: Very High. Coffee chains compete not just with other chains, but with home-brewed coffee, street stalls, convenience-store drinks, tea chains, and bubble tea. Winning requires controlling the total consumption occasion through convenience, social identity, and emotional reward.
SWOT Analysis: Strengths, Weaknesses, Opportunities, Threats
Strengths. Deep local insight, affordable-premium positioning, lower-cost formats, digital-native operations, adaptability, multichannel monetization, regional expansion potential.
Weaknesses. Uneven quality control, concentration risk (domestic revenue dominance), promotional dependence, limited brand universality, supply-chain exposure, experience deficit versus large cafés.
Opportunities. Secondary-city penetration, RTD retail expansion, premium local coffee, corporate and institutional demand, personalization via app data, cross-border expansion, household value propositions for routine beverage consumption.
Threats. Expansion of Luckin and Cotti, potential Starbucks response via pricing and localization, market saturation, input inflation, regulatory and labor pressures, consumer downtrading during economic weakness, brand and data risks.
Real-World Implications: Beyond the Beverage
Implications for Investors and Operators. The most investable growth model is not indiscriminate expansion, but disciplined format selection, margin management, and multichannel monetization. Kopi Kenangan’s return to profitability, US$17 million net profit in 2025 on US$184 million revenue, signals that scale can eventually deliver operating leverage, but unaudited figures require scrutiny. Fore’s rapid revenue growth and successful IPO verify capital market validation of the affordable-premium coffee segment.
Winning White Spaces. The most attractive areas are secondary cities with limited premium coffee, small-format pickup stores near transit and offices, RTD retail distribution, subscription and office programs, localized premium products, and regional markets where adaptation is easily operationalized.
Household Value Proposition. For household-facing platforms, the opportunity is to connect consumers with affordable, reliable, convenient beverage options tailored to routine needs, not just occasional premium experiences. Brands must distinguish between routine and aspirational consumption, prioritizing frequency, local flavor, and digital ease.
Global Playbook Lessons. The convergence of Southeast Asian localization, Chinese operating efficiency, and global premium experience is reshaping retail models. Chains that deliver local relevance at global operational discipline, preserve margins without excessive discounting, and build multiple revenue streams will lead the market.
What Starbucks Still Does Better, and Its Strategic Dilemma
Global Brand Equity and Consistency. Starbucks continues to offer universal recognition, consistent quality, comfortable stores for meetings and work, broad customization, and strong premium credentials. It excels in corporate partnerships and locations tied to travel.
Vulnerability to Local Innovation. Starbucks struggles to match the price, speed, and flavor relevance of local chains. Its challenge is to balance premium positioning with market-specific adaptation. Too much localization can dilute brand equity; too little leaves high-frequency, digitally savvy consumers to competitors.
Chains that build deep local relevance, optimize for digital convenience, and adapt operationally at global scale will not only win Southeast Asia, but define the next era of retail and hospitality worldwide.
Future Trajectory: The Strategic Importance of Southeast Asia’s Coffee Chain Revolution
A New Template for Global Retail. Southeast Asia’s coffee chain evolution is not a regional anomaly, but a blueprint for modern retail: affordable pricing, rapid digital ordering, hyper-local product adaptation, and smaller, delivery-friendly formats. The convergence of Southeast Asian, Chinese, and global strategies is creating a segmentation battle where differentiation depends on operational discipline, margin management, and customer data.
International Expansion and Risks. The challenge for Southeast Asian champions is replicating domestic success abroad, balancing deep localization with scalable procurement and training. Kopi Kenangan’s international push will test whether the “affordable-premium” model can adapt across cultures and market structures.
Investor and Board-Level Imperatives. Boards and operators must prioritize not store count, but mature-store productivity, margin discipline, and channel diversification. The most successful chains will be those that protect unit economics, innovate continuously in flavor and format, and use customer data to drive retention rather than discount wars.
Calling for Strategic Action. As global giants adapt and new entrants multiply, the Southeast Asian coffee chain revolution is a strategic frontier. Leaders must invest in local consumer insight, operational flexibility, and data-driven personalization. Brands that connect daily beverage habits to digital convenience, local meaning, and robust retail economics will not just win in Southeast Asia, but transform the global competitive landscape.
Conclusion: Southeast Asia’s Coffee Chains, Defining the Next Retail Era
Southeast Asia’s homegrown coffee chains are setting new standards for speed, price, local relevance, and digital integration. Their ascendancy marks a strategic inflection point, challenging global giants to rethink premium positioning and operational agility. The region’s affordable-premium innovators have proven that scale can be achieved with discipline, deep localization, and multichannel expansion, offering critical lessons for retail sectors worldwide. As the coffee-and-tea market approaches US$10 billion and growth accelerates, the winners will be those who turn daily beverage routines into sustainable, cross-channel, culturally meaningful experiences. The next retail era will be shaped not by legacy brands, but by those willing to fuse global discipline with local innovation, creating the new gold standard for consumption, convenience, and community.