Gold Refining Squeeze In Switzerland, Germany And London: How Metalor, Heraeus And The Royal Mint Shape Market Entry And Risk For Business Leaders
Gold Under Pressure: Strategic Growth Moves in a Constricted Precious-Metals Refining Market
In the rarefied world of precious metals, cycles of volatility and opportunity go hand in hand. The 2026 surge in gold prices, driven by global economic uncertainty and renewed haven demand, has exposed deep structural challenges within the precious-metals supply chain. For business leaders at Growth HQ and beyond, the story is no longer simply about ounces or spot-price charts. Instead, it is rapidly becoming a tale of capacity bottlenecks, resource nationalism, and the shifting power dynamics between refiners, mints, and distributors. Strategic market entry, risk management, and margin capture now hinge on an ability to adapt to unpredictable global flows, regulatory friction, and a trust-fueled competition for both supply and customers.
Refining Squeeze: When Gold’s Rally Becomes a Bottleneck
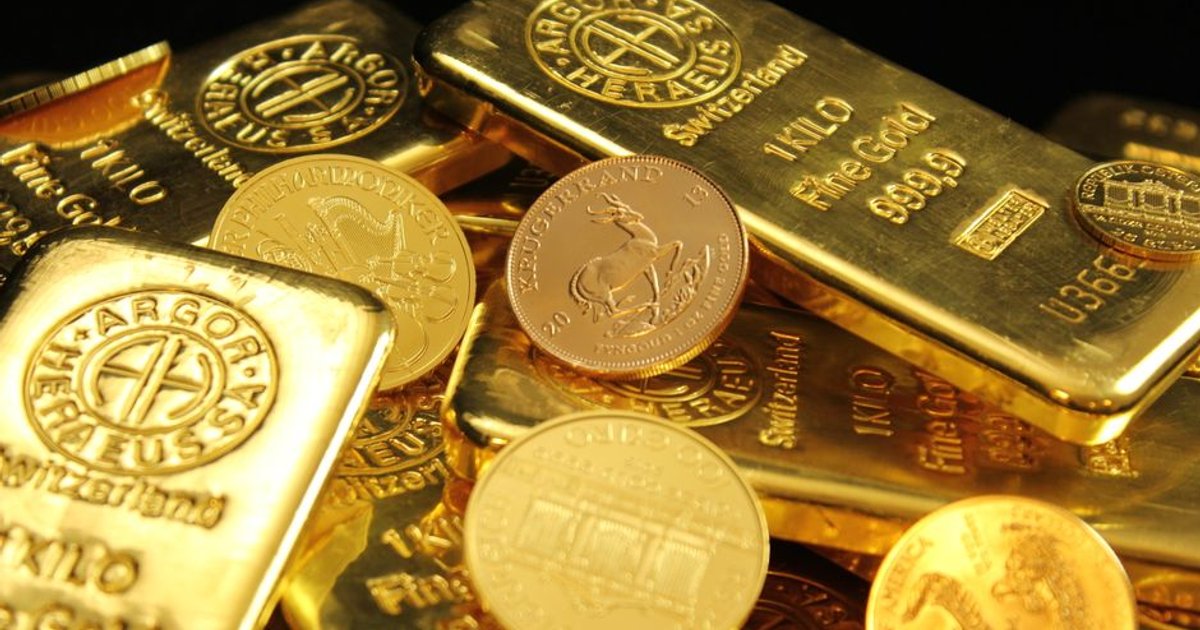
Historic market tension. When gold soared above $4,250 per ounce, the world’s largest refiners experienced a sudden, dramatic influx of scrap and recyclable metal. Normally, upside volatility triggers opportunity; this time, it created a capacity crisis. Major refiners, such as Switzerland’s Metalor and Germany’s Heraeus, were forced to triage demand, restricting onboarding of new clients while prioritizing volumes from established accounts. In the United States, one leading refiner reported that existing-account throughput jumped by 40 percent, while hundreds of would-be clients were simply turned away.
Statistical reality. The surge rippled through the recycling chain. According to industry reporting, global gold recycling increased 5 percent in Q1 as prices spiked, but then declined by 6 percent in Q2 as prices softened and collectors recalibrated expectations. These shifts occur against a backdrop of deeper, structural change, especially as more countries intensify their grip on locally mined commodities.
Resource Nationalism and Regional Playbooks
New barriers, new maps. As gold’s strategic value has grown, so has the emergence of resource nationalism. Asian powerhouses are investing heavily in domestic refining, aiming to keep more of their gold supply within national borders. Indonesia’s announcement of up to a 15 percent export tax on gold underscores this trend, potentially throttling the metal available to global hubs and deepening the strain felt by London and other major bullion markets.
Impact on regional expansion. For business strategists, the implications are profound. Traditional assumptions of frictionless cross-border flows are under threat. Asian producers’ pivot toward in-country value-add represents both a challenge and an opportunity: Western incumbents may lose access to primary supply, yet regional partnerships, joint ventures, and local acquisitions could become the new frontiers for growth. This is not merely resource protectionism; it is a deliberate, strategic reconfiguration of the global value chain.
The Refiners’ Dilemma: Trust, Traceability, and Margin Warfare
Trust as competitive capital. In a crowded bullion market, trust is currency. Business customers are increasingly seeking refiners with impeccable compliance, Good Delivery accreditation, and traceable sourcing practices. Metalor’s recent platinum and palladium market accreditations and Heraeus’s leadership in responsible sourcing set the standard for institutional buyers wary of reputational risk.
Margin innovation amid scarcity. High prices and tight capacity elevate the strategic importance of value-added services. Refiner-owned buyback programs, authenticated resale, and transparency in recycling deductions have emerged as critical levers for capturing premium business, while also enhancing customer stickiness. The current environment rewards operational agility and the branding of integrity at every step of the refining and distribution process.
Comparative Perspectives: How Metalor, Heraeus, and The Royal Mint Shape the High-Stakes Arena
Metalor stands as a classic backbone in the industry, relying on its Swiss heritage, robust compliance standards, and deep technical expertise in metals refining and manufacturing. Now owned by Japan’s Tanaka Kikinzoku Kogyo, Metalor’s institutional focus and newly minted accreditations position it as a supplier of choice for professional buyers and manufacturers seeking maximum assurance.
Heraeus offers a diversified play, extending beyond precious metals into automotive, electronics, industrial, and healthcare applications. The group’s global footprint and market intelligence equip it to serve a range of commercial supply chains. Heraeus can leverage vertical integration and cross-industry insight to pivot faster in response to regulatory or market shocks.
The Royal Mint is distinct: its primary value lies in brand recognition and consumer-facing bullion. While its government-backed status is an asset, it is less equipped to serve industrial and institutional partners during a supply crunch, though it may well see surges in demand for retail gold as household sentiment shifts.
Key strategic difference: The bifurcation in approaches means that professional buyers, manufacturers, and large-scale asset managers will naturally gravitate toward Metalor or Heraeus, while retail and household volumes cluster around The Royal Mint. For those planning international expansion or venturing into wholesale bullion flows, this split in capabilities and customer trust is a central axis of competitive differentiation.
"For forward-thinking leadership, the new market reality is clear: capacity and trust, not just ounces and price, are the ultimate arbitrage in the global precious-metals race."
Strategic Implications: Market Entry, Revenue, and Risk
Securing capacity as strategic wedge. The refining squeeze has transformed access to accredited refining slots into a new kind of competitive moat. Delays not only erode working capital but can fatally undermine market-entry plans, especially for new or expanding players. Business leaders must move quickly to lock in refining agreements, develop multi-supplier contingencies, and monitor processing turnaround times as a leading indicator of wider industry stress.
Margin management and value stacking. High gold prices create windfall opportunities for those able to aggregate scrap, optimize refining deductions, and rapidly recycle capital into fresh inventory. Buyback programs and authenticated resale are no longer optional, they represent a core part of any profitable precious-metals business model.
Regional agility and local partnerships. The era of seamless global arbitrage is waning. Growth-focused organizations must now cultivate in-region alliances and explore joint ventures, particularly in resource-conserving jurisdictions such as Southeast Asia. M&A, co-investment, and technology transfer may become prerequisites to preserving access and navigating export restrictions.
Brand and compliance as growth levers. With institutional buyers demanding visibility into supply chains, accreditations such as Good Delivery and responsible sourcing are not just checkboxes, they are growth multipliers. Firms that demonstrate traceable, compliant practices can command premium pricing and institutional loyalty, while those lacking these credentials risk being shut out of the highest-value markets.
Fluid risk, dynamic mitigation. Tighter working-capital cycles, onboarding delays, and export levies all contribute to a more complex risk landscape. Business leaders must augment traditional hedging strategies with granular scenario planning and real-time supplier diligence, ensuring that their growth trajectories remain robust amidst mounting volatility.
Innovative Practices: Playbooks for Market Leaders
Pre-emptive capacity investment. The most sophisticated market participants are not waiting for crunch time. They are negotiating forward-refining contracts, acquiring minority stakes in refineries, and investing in supply-chain digitization to accelerate throughput and verification. Such moves will give them first-mover advantage the next time demand soars.
Strategic buyback and resale ecosystems. By building trusted and transparent buyback channels, market leaders can smooth revenue volatility and deepen relationships with both retail and institutional clients. Integrated logistics, rapid valuation algorithms, and watertight authentication have become the minimum baseline for success.
Cross-border digital compliance. Digital certification, real-time KYC (Know Your Customer) monitoring, and blockchain-based traceability are emerging as critical enablers for market entry into tightly regulated regions. Organizations that streamline compliance can outpace rivals when onboarding new business beyond their domestic base.
Crisis simulation and supply-chain stress testing. The unpredictable nature of price surges and export restrictions underscores the need for continuous scenario modeling. Leading firms are integrating macroeconomic forecasting, political risk assessment, and supplier stress testing into their standard operating procedures to future-proof their supply positions.
Conclusion: The Next Gold Rush Will Be Won by the Prepared
As the dust settles on the 2026 price surge, the contours of the new precious-metals economy are clear: the most valuable asset is not the gold itself, but the strategic agility to secure, process, and distribute it when others cannot. For business leaders, the imperatives are stark, invest in trusted supply, build redundancy, and use compliance as a lever for competitive advantage. Capacity is no longer a commodity; it is the scarce currency of market leadership. In this environment, only those who anticipate bottlenecks, cultivate partnerships across the value chain, and double down on operational transparency will capture growth in the next chapter of the gold market.
Ultimately, the era of easy international arbitrage is ending. The future belongs to those who can navigate both physical scarcity and institutional trust, capitalizing on every ounce and every opportunity that disruption will bring.