How Starbucks Sustainable Sourcing Model Shapes Global Coffee Supply Chains From Mexico To Indonesia And Thailand
Sustainable Sourcing or Smokescreen? Untangling Starbucks’ Coffee Supply Chain for B2B Buyers and Trade Professionals
The last decade has seen coffee move from a commodity to a symbol of conscious consumption and complex global trade. While consumer-facing brands like Starbucks tout “99% ethically sourced” beans and ambitious sustainability claims, procurement managers and commodity traders know that supply-chain realities are anything but simple. Behind the green packaging lies a web of farms, cooperatives, logistics partners, auditors, and origin-country challenges that raise urgent questions for anyone tasked with sourcing, shipping, or auditing agri-commodities at scale. This exposé dives into the hard evidence behind Starbucks’ sustainable-sourcing model, examining what actually reaches the farm, the port, and the balance sheet, and what remains opaque for those making high-stakes buying and compliance decisions. For the B2B professionals at Good Goods, the question is not just whether coffee is “ethical,” but how traceable, predictable, and compliant these global flows really are, and what this means for where and how to source, process, and move coffee and similar agri-products.
From Field to Vessel: The Complex Reality Behind Starbucks’ Sourcing Model
Scaling Sustainability Across 26 Origins
Starbucks buys roughly 5 million bags of arabica coffee annually, about 3% of the world’s supply, across more than 26 origins in Latin America, Asia Pacific, and Africa. Each origin is not a monolith; it comprises hundreds of thousands of farms, ranging from small family plots in Vietnam and Mexico to larger estates in Brazil and Kenya. For trade desks, this diversity means variable supply risk, inconsistent product attributes, and a host of compliance and price challenges.
C.A.F.E. Practices: A Double-Edged Sword for Buyers
Central to Starbucks’ model is its C.A.F.E. Practices verification system, developed with Conservation International since 2004. Unlike traditional certifications (e.g., Fairtrade, Rainforest Alliance), C.A.F.E. Practices blends economic, social, and environmental criteria and relies on third-party auditors for compliance. The promise for procurement teams: a degree of upstream risk management, especially on issues like deforestation, labor, and supply reliability.
However, the reporting is mostly at an aggregate corporate level, “over 99% compliant” supply chains, which masks crucial details for B2B buyers. There is typically no product-level dashboard showing farm origin, farmer payment, emissions, or compliance red flags for each bag or batch. For procurement, this means that while the system supports risk mitigation at scale, there are persistent black boxes at the level of HS codes, lot-level traceability, and supplier audits.
Value-Addition and Processing: Where the Margins Move
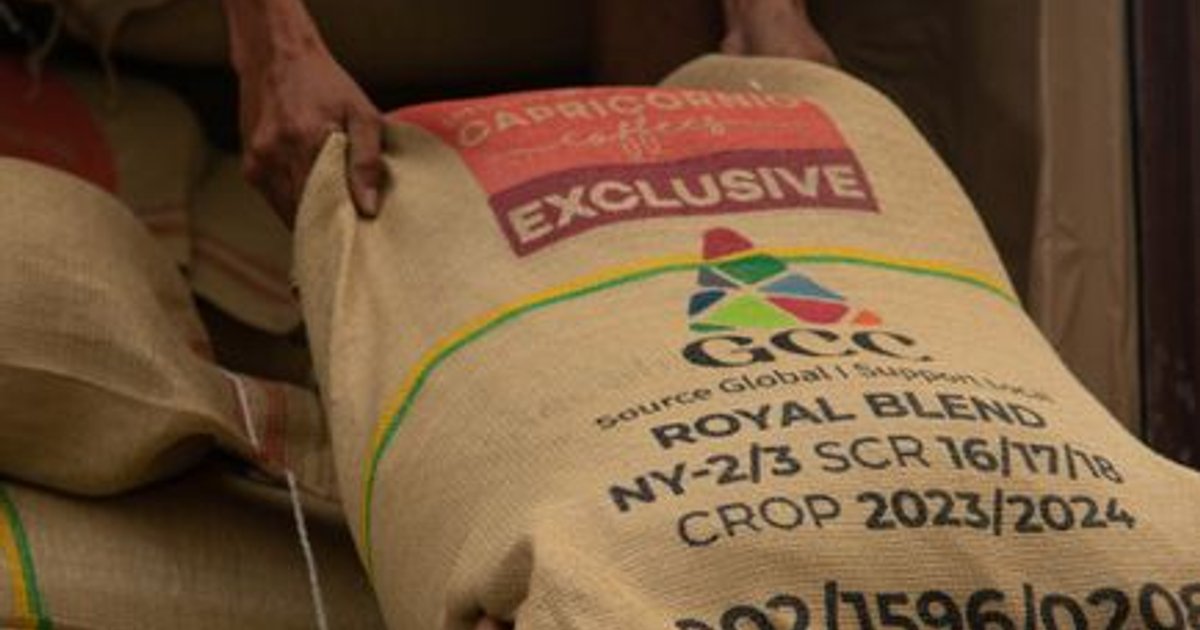
Most Starbucks coffee enters the global supply chain as green, unroasted beans, mapped under HS Code 0901.11 (not decaffeinated) and 0901.12 (decaffeinated). Processing, roasting, blending, packing, typically occurs closer to the end-market, leveraging Starbucks’ proprietary quality controls and brand standards. For origin-based traders and exporters, this positions coffee as a raw (rather than finished) export, subject to origin-country export regimes, local content rules, and potential value-add leakage.
Procurement managers must therefore factor in local processing capacity, port infrastructure, and export controls when selecting supply partners. The more upstream the supply, the greater the risk of disruptions from disease, weather, regulatory shifts, or audit noncompliance.
Key Ports and Shipping Pathways
Starbucks’ sourcing map touches major coffee ports such as Santos (Brazil), Buenaventura (Colombia), Ho Chi Minh City (Vietnam), Sumatra (Indonesia), and Djibouti (East Africa). From these points, coffee moves mainly under Incoterms FOB (Free on Board), with sellers responsible up to port loading and buyers taking on ocean risk and freight, though CIF (Cost, Insurance, Freight) and DAP (Delivered at Place) terms are becoming more common for larger, vertically integrated buyers. Each Incoterm impacts landed cost calculation, insurance needs, and documentary compliance, especially as new EU and US import regulations evolve.
Licensing, Certification and Market Access
While Starbucks’ C.A.F.E. Practices provides one layer of risk mitigation, many importing jurisdictions impose their own requirements. In the EU, Regulation (EU) 2023/1115 on deforestation-free supply chains will soon require geolocation data and rigorous due diligence for coffee (HS 0901) entering the market. The US maintains strict anti-child labor restrictions via the Department of Labor’s supply chain lists. For importers, any break in Starbucks’ (or its vendors’) audit trail can jeopardize customs clearance, lead to shipment holds at ports, or trigger costly audits.
For Vietnam-based traders and logistics managers, flexibility in switching ports (Cat Lai, Hai Phong, Da Nang) and familiarity with export licensing under Circular 16/2018/TT-BNNPTNT (for agricultural product quality) are critical. Sourcing from smaller origins like Papua New Guinea or Ethiopia introduces further complexity; documentation, language barriers, and inconsistent port infrastructure can undermine reliability and traceability.
Lead Times and the Cost of Delays
Coffee’s journey from origin farm to warehouse averages 30 to 90 days, depending on inland transport, port congestion, customs compliance, and shipping lane availability. High-verification regimes (like Starbucks’) can add lead time, as batches undergo extra audit, testing, and approval steps. For supply-chain managers, this increases the importance of buffer stock, flexible contracts, and robust supplier qualification mechanisms.
Decoding the Numbers: What Starbucks Discloses, And What Remains Hidden
Topline Figures with Hidden Variability
Starbucks’ latest Fiscal 2025 Global Impact Report claims that “more than 99%” of its coffee is sourced from C.A.F.E. Practices-verified farms. Yet, those familiar with global agri-commodity trading know that a single percentage can cover wildly different ground realities: from highly organized cooperatives in Colombia to fragmented smallholder networks in East Africa.
Aggregation Masks Country Risk
The report aggregates data regionally, Latin America, Asia Pacific, Africa, without offering consistent country or port-level breakdowns. This leaves buyers with limited insight into which lots might have higher compliance risks or volatility at farm-gate. For instance, Mexico is highlighted for a leaf rust outbreak and subsequent support interventions, but comparable data for other major supplying countries is sparse.
Key Gaps in Payment and Premium Data
What Starbucks does not disclose is as telling as what it does. There is typically no reporting of farm-gate prices, payment timing, quality premiums, or the precise share of value reaching producers. For procurement and risk teams, these hidden economics hinder accurate landed cost modeling and value-add assessments. In markets with heavy price volatility (2022 to 2024 saw arabica futures fluctuate between S$38 to S$100 per 60kg bag), inability to model upstream economics can expose buyers to surprise supplier distress and disruptions.
Verification and Outcomes: Not Always Synced
C.A.F.E. Practices verification confirms process compliance, not outcomes. Even independently audited supply chains might not guarantee living incomes, effective forest protection, or improved working conditions. For B2B buyers, this distinction has regulatory and reputational implications. Compliance teams cannot assume a “verified” lot is always free of risk, as nonconformities and audit failures may be handled privately and not reported at the batch or supplier-specific level.
Inside the System: Regional and Programmatic Insights for B2B Sourcing
Latin America: Disease, Climate, and Programmatic Density
As Starbucks’ major sourcing region, Latin America encompasses both highly organized supply chains and regions with systemic risks, climate shocks, disease outbreaks, and fragmented land tenure. The documented intervention in Mexico illustrates a “verification-to-remediation” model: audit identifies low yields, Starbucks deploys a Farmer Support Center, distributes trees, and provides training. For procurement, such interventions can rebuild supply and stabilize prices, but they are not a guarantee of uniform support across the region or a substitute for transparent, country-specific outcome data.
In practice, much of Latin American coffee for export (HS 0901) moves through major ports like Buenaventura and Puerto Cortes. Export licensing regimes differ by country and can impact who qualifies as a supplier. For Vietnamese or Southeast Asian buyers, these complexities require careful due diligence, particularly as climate risk and disease (e.g., coffee rust) increase supply unpredictability.
Asia Pacific: Technical Support Centers and Infrastructure Bets
The Asia Pacific region sees Starbucks leveraging Farmer Support Centers, hubs like Sumatra’s, to provide agronomic training and field assistance. Local programs, for example, water infrastructure initiatives in Indonesia, demonstrate attempts at supply chain value-add and risk mitigation at origin. Exporters from Indonesia typically move coffee through ports like Belawan and Tanjung Priok, under regulatory scrutiny from both local agencies and destination market import controls.
In emerging origins like Northern Thailand, Starbucks’ three-year program with the Integrated Tribal Development Foundation aims to strengthen smallholder production through technical support. While such initiatives offer evidence of cross-border supply-chain investment, the practical scale remains limited relative to total regional output. For buyers, this means scrutinizing which suppliers participate in such programs and what effect (if any) it has on quality, compliance status, and contract terms.
Africa: Traceability and Value Distribution Challenges
African coffee flows are marked by smallholder networks, complex intermediary chains, and sometimes less-transparent cooperative governance. Ports such as Djibouti and Mombasa are gateways for regional exports, but documentation and payment transparency challenges persist. For B2B buyers targeting direct trade or enhanced traceability, the lack of granular reporting around farm-gate prices, quality premiums, and cooperative participation is a material risk.
Importers must be aware that even robust supplier codes of conduct and third-party audits can be insufficient in regions where record-keeping, access to finance, and land documentation are inconsistent. In such cases, the operational burden of due diligence shifts more heavily onto the buyer or their agents.
Seeing the System from the Inside Out: Diverging Perspectives in the Coffee Trade
Procurement Teams and Supply Chain Managers
From a procurement standpoint, Starbucks’ high-level verification, investment in farmer support, and published sustainability targets appear to offer a robust supply base. But the absence of product-level traceability and country-level economic reporting hinders optimization of cost structures, risk modeling, and compliance mapping. For buyers, “ethically sourced” is not functionally interchangeable with “fully transparent” or “fully de-risked.”
Commodity Traders and Origin Shippers
For traders and exporters at origin, Starbucks’ requirements can be both a boon and a burden. C.A.F.E. Practices status and technical assistance may increase demand for their beans and open premium market access. Yet, the cost and complexity of compliance can squeeze margins, especially for smallholders and cooperatives unable to invest in new record systems or meet evolving deforestation monitoring requirements.
Regulators and Compliance Officers
Regulators see high-level sourcing claims as a partial but insufficient control. The inability to match shipments and lots to precise origin and compliance documentation leaves room for enforcement gaps, especially as new regulations (EU deforestation, US forced labor bans) demand chain-of-custody granularity. Compliance officers must be prepared for challenges in audit readiness, particularly when discrepancies between company-level and farm-level reporting arise.
Investors and Sustainability Auditors
Investors and auditors may find Starbucks’ model forward-looking in its coupling of sourcing with field intervention (support centers, replanting, finance). Still, the strategic risk remains that input and activity reporting (money committed, trees distributed) is mistaken for demonstrated impact (income change, verified environmental recovery). For those staking capital or reputation on supply chain sustainability, outcome measurement remains the missing link.
Civil Society and Watchdogs
NGOs and labor advocates recognize the progress in systematizing sustainable sourcing, but call out the ambiguity in economic, social, and environmental outcomes at the farm level. They push for public dashboards, farmer and worker voice, and remedial transparency when standards are breached.
“Transparency is not only about what companies publish to consumers, but what buyers and regulators can access to validate claims, trace risk, and ensure shared accountability. In the coming era of due diligence regulation, ‘good enough’ traceability will no longer be good enough for those who trade, process, or finance agricultural commodities at scale.”
Practical Sourcing and Trade Implications for B2B Buyers
Origin Selection and Diversification
For buyers and logistics teams, choosing which countries and suppliers to source from is no longer a matter of price and proximity alone. Starbucks’ model shows that investment in farmer support or regional infrastructure can stabilize supply over time, but only if accompanied by transparent reporting and follow-up. In practice, origin diversification, balancing Latin America, Asia Pacific, and Africa, remains essential to hedge against disease, weather, and compliance risk.
Processing Location and Value-Add Decisions
Understanding where value is added, at origin (raw, semi-processed) or in the consuming country (roasted, packaged), influences not only margins, but also compliance pathways, tariff classification, and logistics chain design (e.g., importing green beans vs finished product under different HS codes). Starbucks’ focus on green bean procurement reinforces the need for robust supplier qualification and processing oversight close to export ports.
Incoterms and Shipping Documentation
The choice of Incoterms (FOB, CIF, DAP) directly impacts the distribution of risk and the documentation burden on both supplier and buyer. For C.A.F.E. Practices-verified lots, the added audit steps may require earlier contract closure and more rigorous pre-shipment inspection. Importers must build in buffer time for customs, especially as destination regulations tighten traceability demands (due diligence statements, batch origin data).
Certification and Audit Integration
While Starbucks invests in its own verification, buyers should not rely solely on brand-level certifications for compliance peace of mind. Integrating third-party audits, periodic supplier self-assessments, and randomized field checks remains best practice, especially in regions with known documentation or labor risk.
Cost Structure and Premium Calculation
With farm-gate prices and premium payments seldom disclosed, buyers must estimate the true landed cost using a combination of futures pricing, local market intelligence, and performance benchmarks (yields, input costs, trees distributed). This is especially urgent in high-volatility markets, where input costs or compliance lapses can trigger sudden contract renegotiation or product substitution.
Pre-qualification and Contingency Planning
Supplier pre-qualification should include review of C.A.F.E. Practices documentation, Farmer Support Center engagement, and track record of compliance with new deforestation or labor regulations. Building contingency plans, alternative supply lines, substitute ports, warehousing for risk shipments, is crucial as audit failures or regulatory changes (such as the EU’s upcoming supply-chain due diligence requirements) may disrupt previously stable supplier relationships.
Strategic Actions for Sourcing Teams: From Risk to Resilience
Push for Country-Level and Lot-Level Transparency
Buyers should require Starbucks and similar suppliers to provide country, region, and if feasible, cooperative-level scorecards, covering core metrics like farm-gate prices, verification dates, and scope of farmer support. Where direct disclosure is blocked by commercial or safety concerns, buyers should seek aggregated but actionable risk indicators.
Align Supply Contracts with Sustainability Milestones
Rather than treating sustainability as a check-the-box exercise, embed outcome-linked metrics (e.g., percentage of supply from verified subregions, audit closure rates, tree survival post-intervention) into procurement contracts. Tie pricing or purchasing commitments to improvements in compliance and transparency.
Integrate Technology for Traceability
As digital traceability pilots gain traction (such as those Starbucks has trialed with Conservation International), buyers should advocate for supply-chain data platforms that support batch-level tracking and compliance alerting. This underpins readiness for evolving regulations and strengthens audit readiness at customs and port inspections.
Monitor Regulatory Shifts and Advocate for Harmonization
Keep abreast of new rules (e.g., Regulation (EU) 2023/1115, US forced labor bans) and anticipate shifts in documentation, import licensing, and chain-of-custody protocols. Where regulations diverge, procurement managers should advocate for clarity and harmonization, across agencies, between exporting and importing countries, and among vertically integrated industry players, to avoid supply chain friction.
Prioritize Supplier Enablement and Remediation Partners
The risk with higher verification standards is creating an exclusive club of compliant suppliers while excluding smaller producers or riskier regions. Procurement teams should work with suppliers to fund training, remediation, and documentation upgrades, balancing compliance with supply continuity and cost management.
Leverage Civil Society and Third-Party Data
Augment supplier reports with independent government data, certification audits, field studies, and civil society investigations. This layered due diligence model strengthens both risk detection and the credibility of supply-chain claims, essential as buyers become targets for regulatory and reputational scrutiny alongside brand owners.
Conclusion: The New Due Diligence Frontier in Global Coffee and Agri-Commodity Trade
Starbucks’ sustainable sourcing model represents a significant step in bridging certification, supplier support, and traceability in the global coffee trade. Yet, for procurement, trading, and compliance professionals at Good Goods and across the B2B agri-sector, the system’s opacity at the farm, lot, and shipment level still poses strategic risks. The days of high-level, brand-driven assurances are ending; in their place, regulators, investors, and customers demand granular, verifiable, and accessible data on origin, payment, and impact.
Going forward, suppliers and buyers alike will need to invest in robust traceability infrastructure, data sharing, and contract innovation to meet both regulatory requirements and fast-evolving market expectations. The future belongs to those who move beyond the marketing veneer, leveraging data to optimize sourcing locations, manage risk, lower costs, and transparently prove their value-add at every step from field to vessel. As trade policies tighten and consumer scrutiny intensifies, sustainable sourcing will be defined not by aspiration, but by measurable, auditable, and adaptable supply-chain strategies.
For procurement and trade professionals, the operational edge will come not from slogans, but from hard-won supply-chain intelligence, transforming compliance from a burden into a lever for resilience, market access, and long-term value.